deeper dive: SHOULD I KEEP MY EMERGENCY FUND IN A SAVINGS ACCOUNT OR AN SSB?
1 Oct 2026
SOURCE: CPF Board
Most people default to a savings account for an emergency fund – that’s not a bad choice. But there’s another option worth knowing about: Singapore Savings Bonds (SSBs).
Both are safe and accessible options for your emergency fund. But they work differently, and the right choice depends on your situation. Let’s break it down.
What are Singapore Savings Bonds?
Singapore Savings Bonds are issued by the Singapore Government and managed by the Monetary Authority of Singapore (MAS). They’re designed for individuals who want a safe, flexible place to grow their savings with better returns than a typical savings account.
Here’s what makes SSBs distinctive:
They’re capital-guaranteed. You will get back at least 100% of what you put in, and this is guarenteed by the Government.
They’re offer step-up interest. The longer you hold an SSB, the higher your interest rate gets. Interest is paid out every six months directly into your bank account.
They’re flexible. Unlike most bonds, SSBs allow you to redeem your money at any time with no penalty. You just need to submit a redemption request, and the money will be back in your bank account by the scond business day of the following month.
The minimum investment is $500, and you can invest in multiples. of $500, up to a personal limit of $200,000.
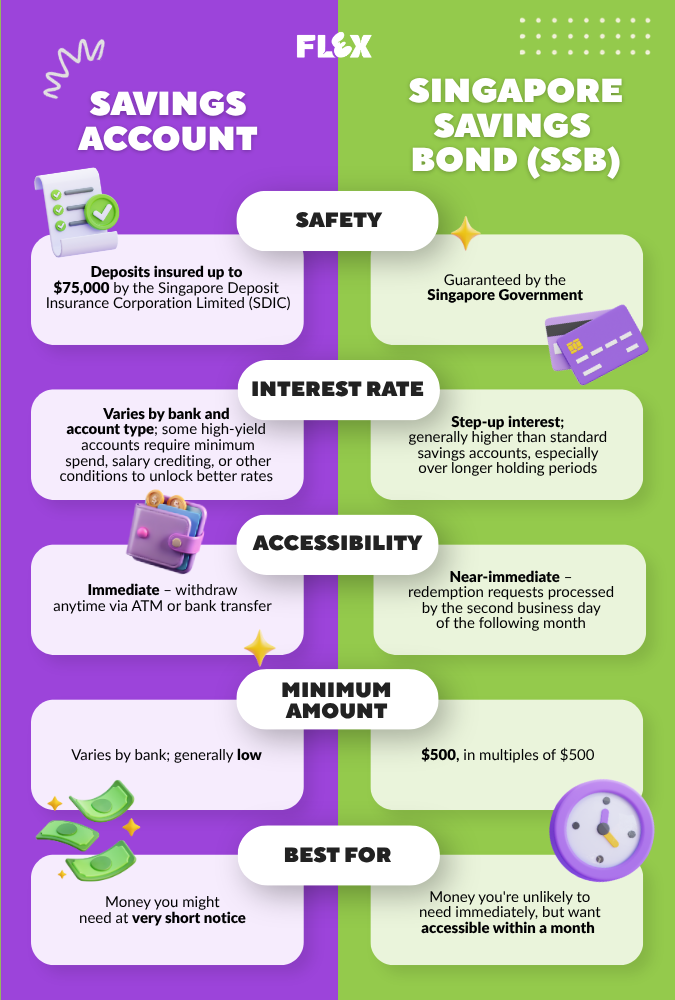
The Comparision
.
So which is right for your emergency fund?
One way to think about it is in layers:
Immediately Accessible
1 to 2 months of expenses in a savings account for urgent use.
Backup Reserves
The remaining emergency fund in an SSB. This would earn you better returns, but still be accessible within a month if needed, and safely out of reach of day-to-day spending temptations.
A NOTE FOR SAFE HARBOURS
If you’re building an emergency fund that covers not just yourself but your family too, the SSB split strategy is worth considering seriously. A larger emergency fund means more money sitting idle – and SSBs are a straightforward, low-effort way to make sure that money is at least earning something meaningful while it waits.
Just make sure your immediately accessible savings account portion is sized for your actual short-term risk – not just your own expenses, but any family commitments you’d need to cover in a genuine emergency.
Want to learn more about SSBs?
MAS has a comprehensive guide to Singapore Savings Bonds, including current interest rates, how to apply, and how redemptions work. Learn more about SSBs.